A route to condo ownership
New ECs combine condominium facilities with eligibility and occupation conditions. Compare actual prices and layouts before deciding.
THE SINGAPORE EC BUYER GUIDE
Start with your question. Understand eligibility, the initial payment and your HDB move—then build a plan around your family.
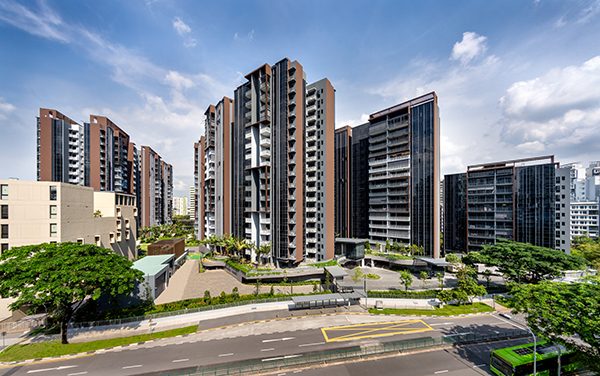
Piermont Grand · Photo: CDL ↗
YOUR QUESTIONS, ANSWERED FIRST
Usually yes, for the initial price payments. BSD and legal fees are extra; the rest is paid later.
See now vs later ELIGIBILITYCheck citizenship, family, income, property interests and past housing subsidies.
Start my quick check HDB UPGRADINGNot necessarily. Compare selling first and renting with keeping your home until the EC is ready.
Compare both routes EC PROJECTSSee the listed launched and final five upcoming old-rule projects, with the rules that matter.
Choose an EC projectTHE OPPORTUNITY, WITH THE TRADE-OFFS
New ECs combine condominium facilities with eligibility and occupation conditions. Compare actual prices and layouts before deciding.
The holding period starts at TOP, after the construction wait. Choose a home that fits your family’s next chapter.
A new EC counts as a housing subsidy even without a CPF grant. A grant is a separate benefit, subject to its own conditions.
FIND YOUR PROJECT
The site’s land tender closing date determines its MOP and payment-rule cohort. Choose a project for a quick comparison.
The launched ECs listed below and the final five upcoming ECs retain the 5-year MOP. New MOP / payment rules apply to sites with tenders closing on or after 8 May 2026.
Choose a project to see its MOP, privatisation timeline, income ceiling and payment options. “Launched” describes the sales stage; it does not confirm remaining units.
| Rule | Old EC rules | Future new EC rules |
|---|---|---|
| Minimum occupation period | 5 years from TOP | 10 years from TOP |
| Full privatisation | 10 years from TOP | 15 years from TOP |
| Monthly household income ceiling | S$16,000 | S$18,000 for tenders closing from 24 August 2026 |
| Deferred Payment Scheme | Developer may offer | Not available |
| First-timer priority | 70% for the first month | 90% for the first 2 years |
Old-rule projects include all six launched projects and the five upcoming entries in this list. MOP, privatisation, priority and payment rules depend on the site’s tender cohort. The income ceiling is S$16,000 for the earlier sites and S$18,000 for tenders closing on or after 24 August 2026. See sources ↗
THE SHORT ANSWER
DPS may be offered only for EC projects whose land tenders closed before 8 May 2026. For sites with tenders closing on or after 8 May 2026, DPS is no longer available. The other 80% follows the agreed deferred schedule, usually from TOP. BSD and legal fees are extra.
With a 75% bank loan, you still need 25% outside the loan in total. The extra 5% is a later payment, subject to your bank and signed contract—not another amount added to the initial 20%.
Show my DPS payment stages →HDB: booking & signing payments ↗The earlier-rule projects listed in this guide include Rivelle Tampines, Coastal Cabana, Otto Place, Aurelle of Tampines, Novo Place and Lumina Grand, plus Wynwood Grand, Solano Grand, Woodlands Drive 17 (Sim Lian), Sembawang Road and Miltonia Close.
DPS depends on the developer’s offer for the unit you choose. Select your project and see its rules ↑
Initial 20% plus fees. The deferred balance is funded by the approved loan and any remaining buyer contribution when due.
An EC quoted under DPS may cost more than under PPS. Enter the actual selected-scheme price in the calculator.
Calculate DPS upfront costs →After the first 20%, payments follow construction milestones. Your bank determines when the remaining equity is paid before loan drawdown.
Loan repayments can start during construction. Allow for overlap with your HDB housing costs.
Calculate PPS payment stages →Price percentages, not cash instalments or dates. Based on the published 2016 statutory form: 20% upfront, 40% construction, 25% TOP-related notice, final 15% under completion / CSC / stakeholder provisions. It is an archived form, not confirmation of your current contract. Your signed S&P, notices and solicitor control.
Public / Fiancé-Fiancée / Orphans / Joint Singles: these are eligibility routes, not payment plans. Fiancé-Fiancée applicants must meet marriage-document deadlines set by HDB / the developer.
CPF Housing Grant / qualifying Citizen Top-Up: specific EC support, not a cash rebate. Grants used for housing form part of the CPF refund with accrued interest on a future sale.
HDB Staggered Downpayment / Deferred Downpayment / contra facilities: do not assume HDB-flat schemes apply to a developer EC. No such facility is included in this model.
Bank bridging finance: may be considered only if a bank offers and approves it. Interest, fees, sale-completion conditions and repayment deadlines are additional; no bridge is assumed here.
YOUR BUDGET
If the preview blocks saving, open this guide in your browser and use the same button.
YOUR ELIGIBILITY
A short preliminary check for a new EC from a developer. Eligibility must be maintained throughout the applicable period, including checks after booking and before TOP.
For a resale EC, this new-launch check does not apply: there is no household income ceiling or CPF housing grant, and buyer nationality depends on the EC’s age. HDB resale EC rules ↗
Use a 12-month assessment of everyone listed in the EC application. The listed earlier-cohort projects have a S$16,000 household ceiling; later sites with tenders closing from 24 August 2026 have an S$18,000 ceiling. Income eligibility and the bank’s loan assessment are separate.
Basic salary, overtime, incentives, allowances, reimbursements, overseas cost-of-living allowances, director’s fees and regular stipends.
Bonus / AWS, savings interest and dividends, maintenance payments, share options, non-cash remuneration, NS allowance, scholarship overseas allowances, pension and rental income.
Variable pay, self-employment, commission income, reimbursements and possible deductions need a document review. Do not apply a bank-income haircut to EC eligibility yourself, or assume an expense can automatically be deducted.
An HFE letter is not required for a new EC application. The linked HFE income page is supplementary reading, not the EC application checklist.
Let us review my income & documents · WhatsApp 8136 6095 ↗YOUR HDB SALE TIMELINE
Compare rental and moving costs with the interest cost of keeping your HDB. Default: 3 years + 6-month buffer.
ROUTE A
—
Illustrative rent + extra move / storage
Cash and CPF can be released sooner. More time to sell, less exposure to a rushed sale near key collection.
Rent does not build home equity. You may move twice. A construction delay can extend your tenancy.
ROUTE B
—
HDB loan interest over the same waiting period
Keep your familiar home and avoid a long rental period. Potentially one move, once the EC is ready.
HDB equity remains tied up. You must fund EC payments and any overlapping mortgages, and complete the HDB sale on time.
THE COST OF RELEASING YOUR HDB FUNDS EARLIER
—
Selling first releases your HDB cash proceeds and reusable CPF sooner. This extra housing cost may make upgrading to an EC possible when you need those funds for the purchase.
HDB principal repayments reduce your debt, so they are shown separately from interest. Check the released funds against your EC payment dates.
Review my sale funds and EC payments ↑HDB’s conditions-after-buying page requires legal disposal within 6 months from EC key collection. Its eligibility page phrases the trigger as completing the EC purchase. Have your solicitor / developer confirm the applicable trigger and exact date in writing. TOP, keys, legal completion and move-in may be different dates.
The extra-cost comparison uses rent + extra move / storage minus HDB interest. It does not compare total mortgage instalments with rent or predict which route is more profitable. Constant monthly inputs are assumptions. HDB price changes, taxes, maintenance, rent stamp duty / deposit, loan penalties, EC payments and interest, CPF opportunity cost and investment returns are excluded. A refundable rental deposit still requires cash. Delay buffer is a scenario, not a forecast.
YOUR DECISION
A FEW MORE ANSWERS
Usually yes, where an eligible older-rule EC developer offers DPS: 5% at booking and 15% at signing are the initial price payments. BSD and legal fees are additional. The remaining 80% follows the deferred contract schedule, usually from TOP. A 75% loan still leaves 25% outside the loan overall; the extra 5% is due later under the bank and developer arrangements.
Compare DPS and PPS ↗The first 5% booking payment requires cash. An approved CPF Housing Grant can offset the next 15% balance downpayment when available through CPF. It is not restricted to payments after the first 20%. Grant approval and availability must match the payment date.
HDB: payment process ↗Not necessarily. An eligible HDB owner may buy a new EC while still owning the HDB, subject to the purchase conditions and disposal deadline. Keeping the HDB does not make its sale proceeds available for earlier EC payments. Plan the completed HDB sale around the applicable deadline and financing arrangement.
Compare HDB sale routes ↗It depends on the land tender closing date. EC sites with tenders closing before 8 May 2026 retain a 5-year MOP; sites with tenders closing on or after that date have a 10-year MOP. The period runs from TOP. Full privatisation is at 10 or 15 years respectively.
HDB: conditions after purchase ↗The listed earlier-cohort EC projects use S$16,000. The S$18,000 ceiling applies to EC sites with tenders closing on or after 24 August 2026. This is separate from how much a bank approves for your loan.
HDB: EC eligibility ↗No. A new EC is financed with a loan from a financial institution, subject to its approval. HDB BTO downpayment schemes and HDB housing loans are different from an EC developer’s payment scheme.
HDB: financing a new EC ↗YOUR NEXT MOVE, AT YOUR PACE
Review your eligibility, a realistic budget and your HDB sale timeline with Vickie. No pressure to book a unit.
SOURCES & VERIFICATION
HDB eligibility reference. Official indexed text retrieved 2 Nov 2026 covers household schemes, SC/SPR requirements, the standard 21/35 age requirements, property restrictions and site-dependent income ceilings. Special cases need individual confirmation.
HDB income-ceiling release. HDB eligibility indexed text retrieved 2 Nov 2026 confirms S$18,000 for EC sites with tenders closing from 24 Aug 2026 and S$16,000 for earlier cohorts.
Official indexed text: 10-year MOP from TOP for tenders closing from 8 May 2026; HDB disposal within 6 months of key collection. The eligibility page uses different wording for the trigger. Confirm exact deadline. Checked 29 Oct 2026.
Official indexed text: earlier/newer ECs open to all buyer nationalities after 10/15 years from TOP; resale ECs have no income ceiling or CPF grant. Checked 29 Oct 2026.
HDB grant page for eligibility and usage. Its mixed first-/second-timer amount table lists SC/SC; the developer’s published Rivelle eligibility booklet separately includes SC/SPR in the Half Housing Grant column. Calculator uses that developer table for the SC first-timer / SPR second-timer estimate, subject to actual grant approval. Citizen Top-Up is not added.
Official indexed process: 5% option payment; 15% balance under OTP timeframe; grant may form part of CPF used for the balance. Checked 29 Oct 2026.
Residential BSD bands effective from 15 Feb 2023; applied on higher price / market value. Cross-checked with IRAS Stamp Duty rate summary, 29 Oct 2026.
Official: conditional automatic remission upon HDB approval where at least one purchaser is SC. Do not apply this model to resale ECs. Checked 29 Oct 2026.
Official: refund principal, accrued interest and applicable pledge; retirement allocation at 55+; market-value sale shortfall treatment. No automatic cash-top-up conclusion in this planner. Checked 29 Oct 2026.
Official: grant used for housing is included in CPF principal refund with accrued interest. Avoid adding it a second time to the refund statement. Checked 29 Oct 2026.
HDB resale levy reference. Confirm liability, the relevant sale/transfer date, payment timing and the applicable fixed or percentage assessment. Earlier sales and complex core-member histories need an individual calculation.
Primary legal text, historical version: source for illustrative milestone percentages only. Current consolidated form was not retrievable. Your signed agreement and solicitor must confirm current timing and stakeholder mechanics.
Secondary report of MND’s 8 May 2026 changes. Use the linked official HDB/MND references for applicability; exact project payment and allocation terms need confirmation.
Referenced official release URL returned a JavaScript / anti-bot page. Not treated as verified source text. See HDB for MOP / resale rules and the secondary CNA report for unresolved payment / allocation details.
Primary PDF lists four upcoming sites, developers and tender closing dates. Its 2 Apr 2026 snapshot predates the Miltonia tender close; it is not the full later pipeline.
Official release gives 14 Apr 2026 tender close, before the 8 May policy cutoff. Checked 29 Oct 2026; separate award notice confirms the successful developer.
Official indexed text confirms award to Hoi Hup Realty on 21 Apr 2026. Miltonia is the fifth upcoming old-rule site added to the older four-site PDF.
Official annex on grant distribution and subsidy treatment from 9 May 2023. Allocation depends on household relationships and application structure; confirm how it applies to the specific EC application.
Developer-published primary booklet, printed pages 6 and 10, checked 2 Nov 2026: Half Housing Grant column covers SC/SC or SC/SPR; footnote applies where spouse/fiancé(e) previously received a subsidy. Income bands give S$15k/10k/5k, zero above S$12k. This is a grant estimate; any future Citizen Top-Up is separate.